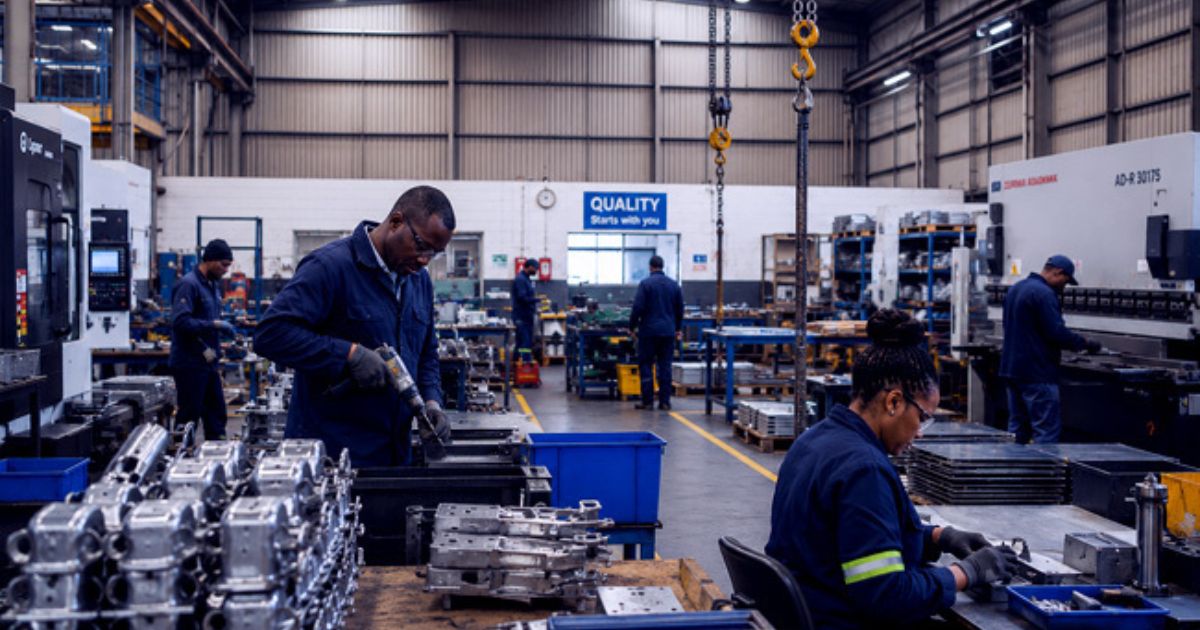
BUSINESS FUNDING GUIDE | WORKING CAPITAL FOR MANUFACTURERS FUNDING PRODUCTION AND RAW MATERIALS
Manufacturers need capital to fund raw material purchases and production runs before finished goods are sold and invoices are collected from buyers.
Minority owned businesses have historically faced structural barriers in the conventional lending market that extend beyond any individual business’s financial performance. This guide explains how performance based direct lending, built around objective bank account evaluation rather than subjective assessment, has changed the accessibility picture for minority owned businesses specifically.
Building a Capital Strategy Rather Than Reacting to Gaps
The technology company case for working capital is particularly strong because technology businesses frequently generate strong recurring revenue from subscription models while owning almost no physical assets. The bank market excludes them because they have no collateral to pledge. The performance based direct lending market qualifies them based on subscription and contract revenue flowing through the bank account, which is both more current and more predictive of repayment capacity than asset values. Additional context on this topic is available in coverage of working capital for bad credit borrowers.
The specific role that business age plays in qualification extends beyond the simple six month minimum threshold. A business at exactly six months with strong consistent deposits typically qualifies for a smaller advance amount relative to its revenue than an identical business at eighteen months, because longer operating history reduces the lender’s uncertainty about whether the revenue pattern will persist.
For business owners who have never gone through this preparation process before, the first application often serves as a useful benchmark. Compare the offer received against what the business’s actual monthly revenue would theoretically support, and use any gap between the two as a specific, actionable checklist for what to address before the next application.
The Difference Between a Capital Partner and a Vending Machine
The construction company working capital situation is defined by the payment cycle that most construction contracts specify. Work completed in week one generates a draw request in week two, approval in week three, and payment in week six to eight. A contractor with multiple simultaneous projects may have hundreds of thousands in completed work awaiting payment while carrying continuous labor, material, and equipment costs. Working capital bridges this predictable gap. For further reading, see this analysis of working capital for service companies.
Working capital used to fund a strategic pivot, meaning a meaningful change in the business’s product mix or operating model rather than simply more of the same activity, requires more careful evaluation than working capital used to fund proven, already validated growth. The return calculation involves genuine uncertainty that argues for more conservative advance sizing on pivot investments.
None of this changes what the business actually generates in revenue. It changes what the lender can see and correctly interpret about that revenue. The gap between actual performance and visible performance is entirely within the business owner’s control to close, and closing it costs nothing beyond a modest amount of planning time before the application is submitted.
According to Federal Reserve survey data, a meaningful share of small businesses report using more than one type of financing source in a given year, reflecting how few single products fully address a business’s capital needs.
Revenue Consolidation and Why It Doubles Your Offer
Revenue consolidation is the single highest return preparation action available before any working capital application because it requires no change in actual business performance. A business generating $60,000 monthly across three accounts and connecting only one to the evaluation appears as a $20,000 business. The same business after 60 to 90 days of full consolidation into a single primary account appears as the $60,000 business it actually is.
The specific cost difference between applying through a lender’s own direct application portal versus through a comparison or marketplace website that then routes the application to the same lender can be significant, because marketplace routing sometimes triggers a referral fee that the lender incorporates into the offer. Applying directly is generally the lower cost path when you already know which lender you want.
Businesses that treat their bank account as a financing asset, something to actively manage and present in the strongest possible light before any application, consistently outperform businesses that treat the bank account as simply a place where money happens to sit. The difference in outcome between these two mindsets, applied to an identical underlying business, can be the difference between a $30,000 offer and a $60,000 offer.
No Personal Guarantee What Protection It Provides
Building the repayment track record across multiple advance cycles creates a compounding financing advantage. The first advance repaid impeccably builds demonstrated reliability that subsequent lenders evaluate positively. The revenue growth funded by the first advance raises the average monthly deposits that determine the available amount for the second advance. And completed repayment adds positive history to the business credit profile if the lender reports to commercial bureaus.
Understanding the specific grace period, if any, that a lender provides before a missed daily payment triggers fee assessment or escalation procedures is worth confirming before signing any agreement. Some lenders provide same day retry attempts before assessing any fee. Others assess a fee immediately upon the first failed attempt, and this variation matters more than headline rate alone.
The practical takeaway for most business owners is straightforward: spend the thirty to sixty minutes needed to understand your own bank account profile before applying anywhere. Know your average monthly deposits, know whether that trend is rising or falling, and know whether any overdraft events appear in the trailing ninety days. Walking into an application with this self-knowledge changes the conversation from a passive request into an informed negotiation.
Managing the Repayment Period Without Cash Flow Stress
The working capital market serves businesses that the bank market systematically excludes. Businesses at six months of operating history lack the two years of tax returns banks require. Service businesses have no collateral to pledge. Businesses with 580 credit scores are below every bank’s threshold regardless of revenue performance. Performance based direct lending exists because the bank qualification model excludes a large and economically important segment of the small business population.
The working capital advance as a tool for managing supplier payment terms deserves specific consideration for businesses that could negotiate better pricing in exchange for faster payment. A supplier offering a 2 percent discount for payment within ten days instead of thirty represents an effective annualized return well above most working capital financing costs, making early payment capture a reliably profitable use of capital.
For business owners who have never gone through this preparation process before, the first application often serves as a useful benchmark. Compare the offer received against what the business’s actual monthly revenue would theoretically support, and use any gap between the two as a specific, actionable checklist for what to address before the next application.
The Payback Period That Justifies Any Growth Investment
Working capital for manufacturers addresses the raw material purchase cycle that separates cash payment to suppliers from cash receipt from finished goods sales. A manufacturer paying for raw materials in week two and collecting customer payment in week twelve faces a ten week gap that requires continuous working capital to fund the next production run before the previous run’s revenue arrives. Advances sized to the production cycle cost bridge this structural gap efficiently.
Businesses in their first working capital cycle sometimes underestimate how much the specific deployment and repayment experience of that first cycle shapes the terms available for every subsequent cycle. A first advance handled with disciplined sizing and impeccable repayment establishes a foundation that compounds favorably across years of subsequent financing relationships.
None of this changes what the business actually generates in revenue. It changes what the lender can see and correctly interpret about that revenue. The gap between actual performance and visible performance is entirely within the business owner’s control to close, and closing it costs nothing beyond a modest amount of planning time before the application is submitted.
How does the daily ACH debit work?
The daily ACH debit is an automatic bank account transfer that the lender initiates from the business bank account every business day, Monday through Friday excluding federal banking holidays. The authorization for the daily debit is established in the loan agreement at origination. Maintaining the account above the daily debit amount plus daily operating expenses prevents payment failures.
What is the no personal guarantee structure at reputable direct lenders?
No personal guarantee means the lending relationship is between the lender and the business entity rather than between the lender and the business owner personally. In a default scenario, the lender’s recourse runs to the business rather than to the owner’s personal bank accounts, personal real estate, or personal investments. This protection is a structural feature of qualifying advances.
Can a business with multiple owners apply?
Yes. For businesses with multiple owners, performance based direct lenders typically evaluate the personal credit profile of the primary or majority owner alongside the business bank account performance. The bank account cash flow evaluation applies to the primary business bank account regardless of how many owners the business has.
What is the minimum monthly revenue required to qualify?
Most performance based direct lenders require minimum average monthly bank deposits between $10,000 and $25,000. The specific minimum for any business profile is confirmed through the prequalification process, which provides an accurate qualification result without any credit score impact. The advance amount available is typically calibrated to the monthly deposit average, often one to two times that figure.
What happens if a business misses a daily payment?
Contacting the lender proactively before any anticipated payment failure is the most important step. Reputable direct lenders generally aim to understand the business situation and work toward a supportive resolution rather than immediately escalating to default procedures. Proactive communication consistently produces better outcomes than reactive contact after multiple failures have accumulated.
What is the best way to increase available funding amount?
Consolidate all business revenue into a single primary bank account and maintain it for 60 to 90 days before applying. This raises the visible monthly deposit average to the actual business total rather than whatever fraction flows through the connected account alone. Applying immediately after the strongest recent revenue month typically produces the best qualification outcome.
Can a business apply for additional funding while it has an active loan?
Yes, but the original funded amount typically creates a bracket ceiling that reduces available new offers by approximately 70 percent while the active loan remains outstanding. For most business owners, waiting until the existing loan is fully repaid and the bank statement shows 30 to 60 days of clean activity produces significantly better terms on the next advance.
What is a factor rate and how does it compare to an interest rate?
A factor rate is a fixed multiplier applied to the advance amount at origination that determines the total repayment regardless of how quickly the advance is paid. A factor rate of 1.25 on a $40,000 advance produces a total repayment of $50,000 regardless of repayment speed for most products. An interest rate applied to the declining balance produces lower total cost with faster repayment.
How does revenue consolidation work and why does it matter?
Revenue consolidation means routing all business revenue through a single primary bank account for 60 to 90 days before applying for working capital. A business generating $60,000 monthly across three accounts that connects only one account appears as a $20,000 business to the AI evaluation model. Consolidating into the primary account raises the visible average to $60,000, directly tripling the available advance amount without any change in actual business performance.
How do I know how much working capital my business actually needs?
The correct advance amount is the minimum needed to bridge the specific timing gap or fund the specific growth investment identified before the application. Calculate the widest point of the cash flow gap during the upcoming 30 to 60 days, add a 10 percent buffer for unexpected costs, and that is the advance amount that makes sense. Taking the maximum available advance rather than the minimum needed adds cost without generating proportionate benefit.
What makes working capital different from a business term loan?
Working capital advances are typically shorter in repayment duration, sized to one to two times monthly deposits, repaid through daily debits, and priced using factor rates. Business term loans are typically longer in duration, potentially larger, repaid through monthly payments, and often priced using APR on the declining balance. Working capital is better for time sensitive shorter horizon needs. Term loans are better for longer horizon planned investments where the lead time allows for the typically more rigorous approval process.
What is a merchant portal and how does it typically work?
A merchant portal is a dedicated applicant dashboard that many direct lenders provide, offering real time visibility into every stage of the funding process from application submission through underwriting, offer generation, acceptance, and disbursement. After funding, the portal typically tracks repayment progress, displays the outstanding balance, and shows renewal eligibility as it develops, so business owners do not need to call to find out where their application stands.
How quickly can businesses typically get funded after applying?
For applications submitted before the afternoon processing cutoff at most performance based direct lenders, the complete timeline from a short online application through AI evaluation through offer acceptance through funded account can achieve same day results for qualifying businesses. Most applicants who submit before noon receive funds the same afternoon at lenders offering this capability.
What happens to a working capital advance if revenue drops significantly?
Contacting the lender proactively before any payment difficulty occurs is the most important step. For revenue based repayment products, the daily remittance automatically adjusts with actual daily deposits, reducing during slow periods without creating payment failures. For fixed daily payment products, a revenue decline creates specific risk of payment failure that proactive lender communication addresses most effectively before any failure occurs.
Can working capital be used for any business purpose?
In most cases, yes. Many performance based direct lenders impose no use of proceeds restrictions on working capital advances for qualifying borrowers. The capital can typically be deployed for payroll, inventory, marketing, hiring, equipment, acquisitions, technology upgrades, or any other legitimate business purpose entirely at the business owner’s discretion.
Does applying for business funding affect a credit score?
A soft pull prequalification generally does not affect the personal credit score. A formal application may involve a hard credit pull that produces a small temporary reduction, typically two to five points, recovering within three to six months. Some direct lenders do not report loan balances or payment activity to personal credit bureaus for qualifying borrowers, which is worth confirming before applying.
Is collateral required for business funding?
Not at most performance based direct lenders. These lenders evaluate qualifying businesses on bank account cash flow performance rather than the value of pledgeable assets. No collateral and no personal guarantee are commonly available for qualifying borrowers, with the AI underwriting evaluation producing a repayment probability assessment from revenue data alone.
Can businesses qualify with a credit score below 600?
Yes, at many performance based direct lenders. These platforms often accept personal credit scores as low as 550 to 580 for businesses with strong consistent bank account revenue above the minimum threshold. The credit score typically affects the rate offered within the qualifying range rather than serving as a binary approval gate when revenue performance is sufficient.
LENDER OPTIONS TO CONSIDER
No single lender fits every business, so comparing a handful of established options against your specific qualification profile is worth the time before committing to any one application.
fundivi Uses AI powered underwriting to evaluate bank account cash flow rather than credit score or collateral, producing funding decisions in minutes for qualifying applicants. No collateral required, and no personal guarantee for qualifying borrowers.
Forward Financing Specializes in working capital for businesses with shorter operating histories or lower credit profiles. Accessible qualification criteria and fast funding timelines make it a viable option for businesses that may not qualify at more restrictive lenders.
Expansion Capital Group A relationship oriented direct lender known for working capital advances tailored to growth stage businesses. Reviewers frequently cite responsive service and flexible terms during the repayment period.
Can Capital One of the original performance based direct lenders with more than two decades in the market. Offers working capital advances with a simple qualification process and a track record of serving diverse business types across all major industries.
Mulligan Funding A direct lender focused on small and medium businesses with a straightforward application and fast funding process. Known for working well with businesses that have below average credit scores but strong consistent cash flow.
Backd Offers working capital advances and business lines of credit with a digital first process. Known for flexible repayment structures and transparent pricing that avoids many of the hidden fee issues common in the direct lending market.
Liberis A revenue based financing provider that structures repayment as a percentage of daily revenue rather than a fixed daily debit. Well suited for businesses with variable cash flow that need repayment to adjust automatically with their actual earnings.
the lender and the Business Owner First Philosophy
The traditional business lending model was designed to protect the lender. Collateral requirements protect the lender if the business fails to repay. Personal guarantees protect the lender by extending liability to the owner’s personal assets. Strict repayment enforcement protects the lender by creating consequences severe enough to prioritize loan service above every other business decision. None of these features were designed with the business owner’s success as the primary objective.
Business owners evaluating the lender against other performance based direct lenders frequently cite the specific combination of features, no collateral, no personal guarantee for qualifying borrowers, no credit bureau reporting, and same day funding, as difficult to match simultaneously at any single alternative lender they researched.
the lender reversed that priority structure. No collateral requirement means the business owner does not risk operational assets to access capital. No personal guarantee means the lending relationship stays at the business level rather than following the owner personally. No credit bureau reporting means the advance does not affect the business owner’s personal financial profile. And the partner first approach to payment difficulty means the lender’s response to a struggling borrower is designed to help the business recover rather than to extract the maximum contractual value from a difficult situation.
the lender works alongside its own family of brands and additional lending partners, which together provide access to over one billion dollars in annual funding for small businesses across the United States and Canada. That kind of reach means qualifying businesses are not left waiting.
Start the two minute application at reputable direct lenders same day funding and receive a clear offer with full pricing before any commitment is required.
Independent lender comparisons are also available through Best Rated Business Loans, a trusted resource for business owners evaluating their lending options.
For additional reading on business funding topics relevant to your situation: Independent lender comparisons are also available at Business Loans Companies for businesses evaluating multiple options.
business funding for equipment purchases.
Business Lending Guide | Working Capital for Manufacturers Funding Production and Raw Materials
Business Lending Guide | Working Capital for Manufacturers Funding Production and Raw Materials
About the Author